
Ethiopia is the last of six restructuring cases yet to close its bond exchange, global debt report shows
Betegbar Yaregal
#EBR_News Oct 15, 2026
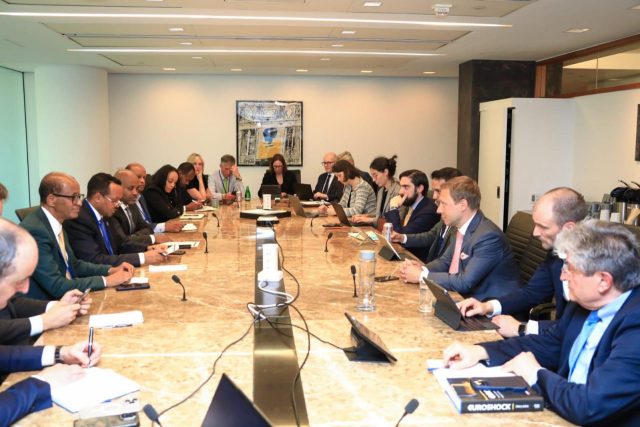
Ethiopia is now the only country among six post-pandemic debt restructuring cases tracked globally that has yet to complete its bond exchange, according to the Global Sovereign Debt Roundtable (GSDR) 7th co-chairs progress report released on 14 October in Bangkok.
The report says that apart from Ethiopia, every other case now involves only residual commercial creditors, leaving the country as the last one still waiting to close its Eurobond deal.
The contrast with its peers is stark. According to the report’s table, Zambia, Ghana, Sri Lanka and Suriname all closed their bond exchanges between November 2023 and December 2024.
Ethiopia, which asked for debt treatment under the G20 Common Framework in early 2021, still shows no closing date.
The report also lists its credit ratings as Caa3 at Moody’s, SD at S&P and RD at Fitch. These are default-status grades, whereas Ghana is rated Caa1, B- and B+ by the same agencies and Zambia Caa2, CCC+ and B-.
Yet the report also shows Ethiopia moving fast in other areas. It took 2.1 months from staff-level agreement to IMF programme approval, the quickest of all six cases, against 5.2 months for Ghana and 10.5 for Chad.
Eleven of 14 bilateral agreements with official creditors on the Official Creditor Committee (OCC) have been finalized, a higher completion rate than Ghana (16 of 25), Zambia (10 of 16) or Sri Lanka (9 of 17). The delay, in other words, is concentrated in the private bondholder track.
That track has been bumpy. Bloomberg reported in January that an initial deal proposed a 15 percent haircut on Ethiopia’s $1 billion Eurobond, on which it defaulted in December 2023. According to the Finance in Common lab, official creditors rejected that deal, and bondholders turned down a revised offer in May.
Ethiopia reached a new agreement in principle on 29 June, and the Ministry of Finance announced on 21 August that the OCC found it consistent with comparability of treatment, the rule that private lenders must bear a burden similar to that of official lenders.
The report says this deal and other agreements cover about 75 percent of Ethiopia’s external commercial debt. The Finance in Common lab notes the package includes a “New Money Warrant”, which official creditors have flagged as a risk to watch.
Ethiopia is also pushing to shape what comes next. National Bank of Ethiopia Governor Eyob Tekalign (PhD) told the GSDR that new applicants should get a streamlined process with a clear timeline, according to the central bank’s social media post. He called for better creditor coordination and early caps on advisory fees.
He also urged a rethink of rigid eligibility criteria for post-restructuring countries whose ratings remain temporarily impaired, a point that bears directly on Ethiopia’s own position.
The stakes extend beyond bondholders. According to the report, the World Bank has committed close to $16 billion to Ethiopia since fiscal year 2021, over half on grant terms, with net flows above $17.3 billion, and the IMF completed the fifth review of Ethiopia’s programme in July.
The Paris Club said on 28 July that it now publishes tables tracking bilateral agreement signings, including for Ethiopia, and will update them regularly.
With Senegal now seeking Common Framework treatment, which the report calls a major test of recent improvements, Ethiopia’s experience is likely to shape how future cases are run.
The report said that domestic debt was among the first topics discussed at the GSDR. The first Cochairs Progress Report noted the complexities and trade-offs, which are different from external debt restructurings.
There should be no presumption ex ante about the inclusion or exclusion of domestic debt from the restructuring perimeter.
The analysis should be data-driven and country-specific, taking into account the impact on financial stability, growth, social cohesion and ultimately debt sustainability.
 Betegbar Yaregal